💳 Pay Now |
✍️ Learning Center
Your head office and your branch are one company in the eyes of company law, but two different persons under GST. That single rule decides whether internal transfers are taxable and how they must be valued. Here is the plain-language guide.
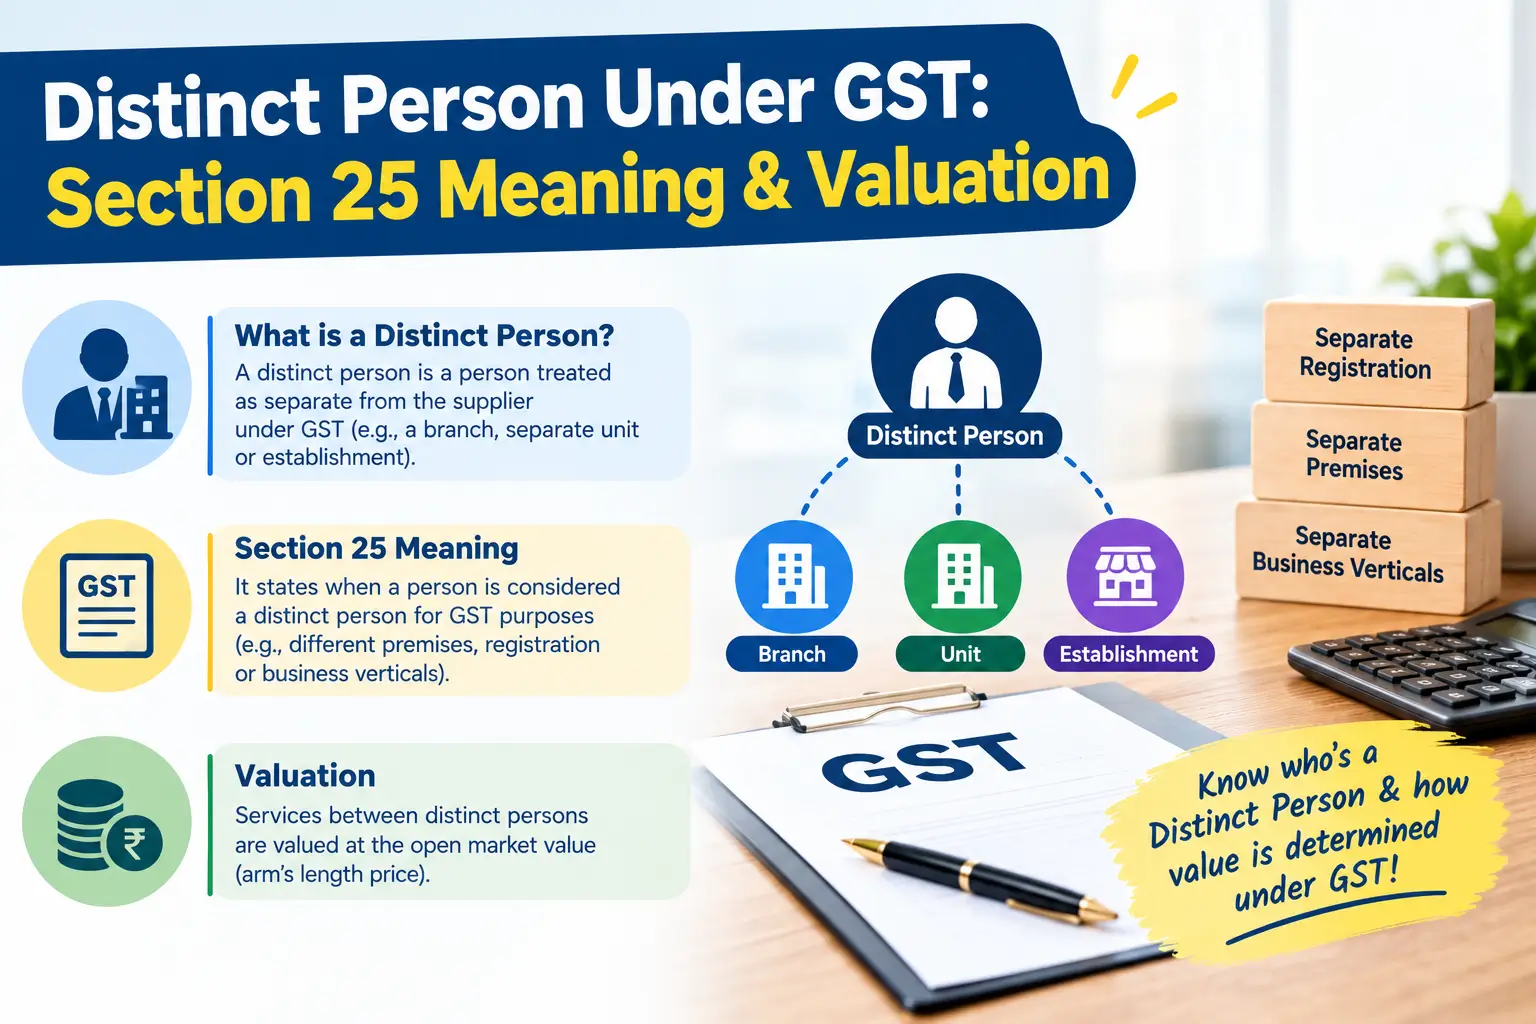
Quick Answer: Under Section 25 of the CGST Act, every GST registration held by the same person is a distinct person, and a business's establishments in different states are treated as establishments of distinct persons. Supplies between them made in the course or furtherance of business are taxable even without consideration under Schedule I, and they are valued under Rule 28: open market value first, then like kind and quality, then cost plus 10% and the residual method. Where the recipient has full input credit, the invoice value is deemed to be the open market value.
In company law, a business is one legal person. GST deliberately breaks that apart. A company with a factory in Gujarat and a sales office in Karnataka will hold two GST registrations, and for the purposes of GST those two registrations are treated as separate persons. They file their own returns, pay their own tax and keep their own credit ledgers. When one sends goods or services to the other, GST treats it like a supply between strangers, even though both belong to the same company.
This is the rule behind several everyday questions: Is a branch transfer taxable? Do I charge GST on my head office's management services? What value do I put on the invoice? If you are adding states, our GST registration services across India page explains how each registration is created.
| Situation | How GST treats it |
|---|---|
| One person holds more than one registration, in the same state or different states | Each registration is treated as a distinct person for the purposes of the Act |
| A person registered for an establishment in one state has an establishment in another state | The establishments are treated as establishments of distinct persons |
| A business registers separate business verticals within a state | Each vertical registration is a separate registration and so a distinct person |
| Employee providing services to employer in the course of employment | Not a supply under Schedule III; not a distinct person issue |
Section references and wording are summarised in plain language. Check the CGST Act directly for the exact text.
Schedule I of the CGST Act lists activities treated as supply even without consideration. One entry covers supplies of goods or services between related persons or between distinct persons under Section 25, when made in the course or furtherance of business. That means a branch can owe GST on goods or services it sends to another branch even if no money changes hands.
| Flow | Usually a supply? | Why it matters |
|---|---|---|
| Stock transfer to a branch in another state | Yes | IGST is charged; the receiving branch can claim credit if eligible |
| Head office management services to a branch | Yes, where internally generated and made in the course of business | Cross-charge invoice and valuation needed |
| Common third-party input services shared by branches | Not a supply; a credit distribution question | Handled through the ISD mechanism |
| Employee salary within one registration | No, employment is outside supply | No invoice is needed for the salary itself |
| Transfer between two registrations in the same state | Yes, as distinct persons | Needs a tax invoice and valuation |
Rule 28 of the CGST Rules sets the order in which the value of a supply between distinct or related persons is determined, when the supply is not made through an agent.
| Order | Method | In simple terms |
|---|---|---|
| 1 | Open market value | The value an unrelated buyer would pay an unrelated supplier for the same supply |
| 2 | Value of like kind and quality | If open market value is not available, use goods or services of a similar kind and quality |
| 3 | Cost-based method (Rule 30) | Generally 110% of the cost of production, acquisition or provision of the service |
| 4 | Residual method (Rule 31) | Applied where the earlier methods do not give a value; for services, the supplier can go to this method directly |
| Option | 90% rule | If the recipient resupplies the goods as such, the supplier may choose 90% of the price the recipient charges unrelated customers for like goods |
| Proviso | Full input credit | Where the recipient is eligible for full input tax credit, the value declared in the invoice is deemed to be the open market value |
Rules can be amended by notification. Confirm the current text and your own facts before relying on any method.
A head office in Delhi provides IT support to a branch in Pune, with a cost of ₹1,00,000 for the month. If the branch has full Input Tax Credit, the head office can invoice at the value it declares, and the invoice value is treated as the open market value. If the branch cannot claim full credit and no open market value exists, the cost-plus approach would give 110% of ₹1,00,000, which is ₹1,10,000. The numbers are illustrative only; your own method depends on the facts.
Used when one registration supplies goods or services to another. It means a proper tax invoice, valued under Rule 28, with GST charged and reported in both sets of returns.
Used to distribute input credit on common third-party services, such as a shared audit or software licence, across branches. The ISD mechanism is now the prescribed route for common input services.
Cross-charge applies to what the head office itself produces. ISD applies to what it buys from outside and passes on. Using the wrong one creates credit problems.
Cross-charge invoices, the basis used for valuation, ISD invoices and distribution records, and a reconciliation between registrations.
| Basis | Distinct person | Related person |
|---|---|---|
| Source | Section 25 of the CGST Act | Explanation to Section 15 of the CGST Act |
| Typical example | Head office and branch with separate registrations | Associated companies, relatives, partners in the same firm, or persons where one controls the other |
| Taxed when | Supplies in the course or furtherance of business, even without consideration | Supplies between related persons made in the course or furtherance of business |
| Valuation | Rule 28 | Rule 28 |
List every GSTIN under your PAN, including separate registrations in the same state, and note which establishment sits under which one.
Mark goods moved, services shared and costs recharged between registrations, because each is a potential supply.
Choose tax invoices for each internal supply and check whether the recipient has full input credit, which affects the valuation approach.
Work through open market value, like kind and quality, and the cost-based methods, and document the basis you used.
Use the ISD mechanism for common third-party input services and cross-charge for internally generated services.
Show internal supplies in each GSTIN's returns and reconcile them so the sender's output tax and the receiver's credit match.
Distinct person questions are where small mistakes turn into audit queries, because they involve money moving inside one business. Our team of Chartered Accountants and Company Secretaries maps your registrations, checks every internal flow and sets up invoicing and valuation that you can defend. We also help you with updating your GST registration details when branches change and the GST cancellation process when a registration is closed.
Businesses with several establishments often need these services as well:
What is a distinct person under GST?
Under Section 25 of the CGST Act, each GST registration held by the same legal person is treated as a distinct person. Establishments of one business in different states are also treated as establishments of distinct persons, even though they belong to the same entity.
Is a supply between head office and branch taxable under GST?
It can be. Where the head office and branch hold separate registrations and the supply is made in the course or furtherance of business, Schedule I treats it as a supply even without consideration, so GST can apply.
Are stock transfers between my states taxable?
Yes. Moving goods between separate state registrations of the same PAN is treated as a supply between distinct persons and is generally taxed as an inter-state supply, with IGST charged on the invoice.
How is the value of a supply between distinct persons determined?
Rule 28 applies. The starting point is open market value, then value of like kind and quality, then the cost-based and residual methods under Rules 30 and 31. A 90% option exists when the recipient resupplies the goods as such.
What is the cost-plus method under Rule 30?
Where open market value and like-kind value are not available, the value is generally taken as 110% of the cost of production, manufacture or acquisition of goods, or of the cost of providing the services.
When can the invoice value be treated as open market value?
When the recipient is eligible for full input tax credit, the value declared in the invoice is deemed to be the open market value. This is why many businesses with fully taxable recipients use the invoice value.
Is salary paid to employees treated as a supply between distinct persons?
Services by an employee to the employer in the course of employment are not treated as a supply under Schedule III. Cross-charge questions arise for internally generated services such as management support from a head office.
What is cross-charge and when is it needed?
Cross-charge means raising a tax invoice from one registration to another for services or goods supplied between them. It is relevant for internally generated services between separate registrations and for stock transfers.
How does the Input Service Distributor mechanism fit in?
For credit on common input services received from third parties, the ISD mechanism is now the prescribed route to distribute credit to branches. Cross-charge continues to apply to internally generated services.
Can SetupFiling.in help with distinct person and valuation questions?
Yes. Our CA team can review your registrations, inter-state transfers and head-office services, advise on valuation and set up invoicing. Message us on WhatsApp at +91 98182 09246 to get started.
Join 50,000+ customers who trust SetupFiling.in for CA-assisted GST guidance.